Guides14 min read
CNC Machine Finance UK: Hire Purchase, Leasing & Funding Options
Explore the main ways UK businesses may finance new or used CNC machinery, including hire purchase, leasing and asset refinance.
Tera
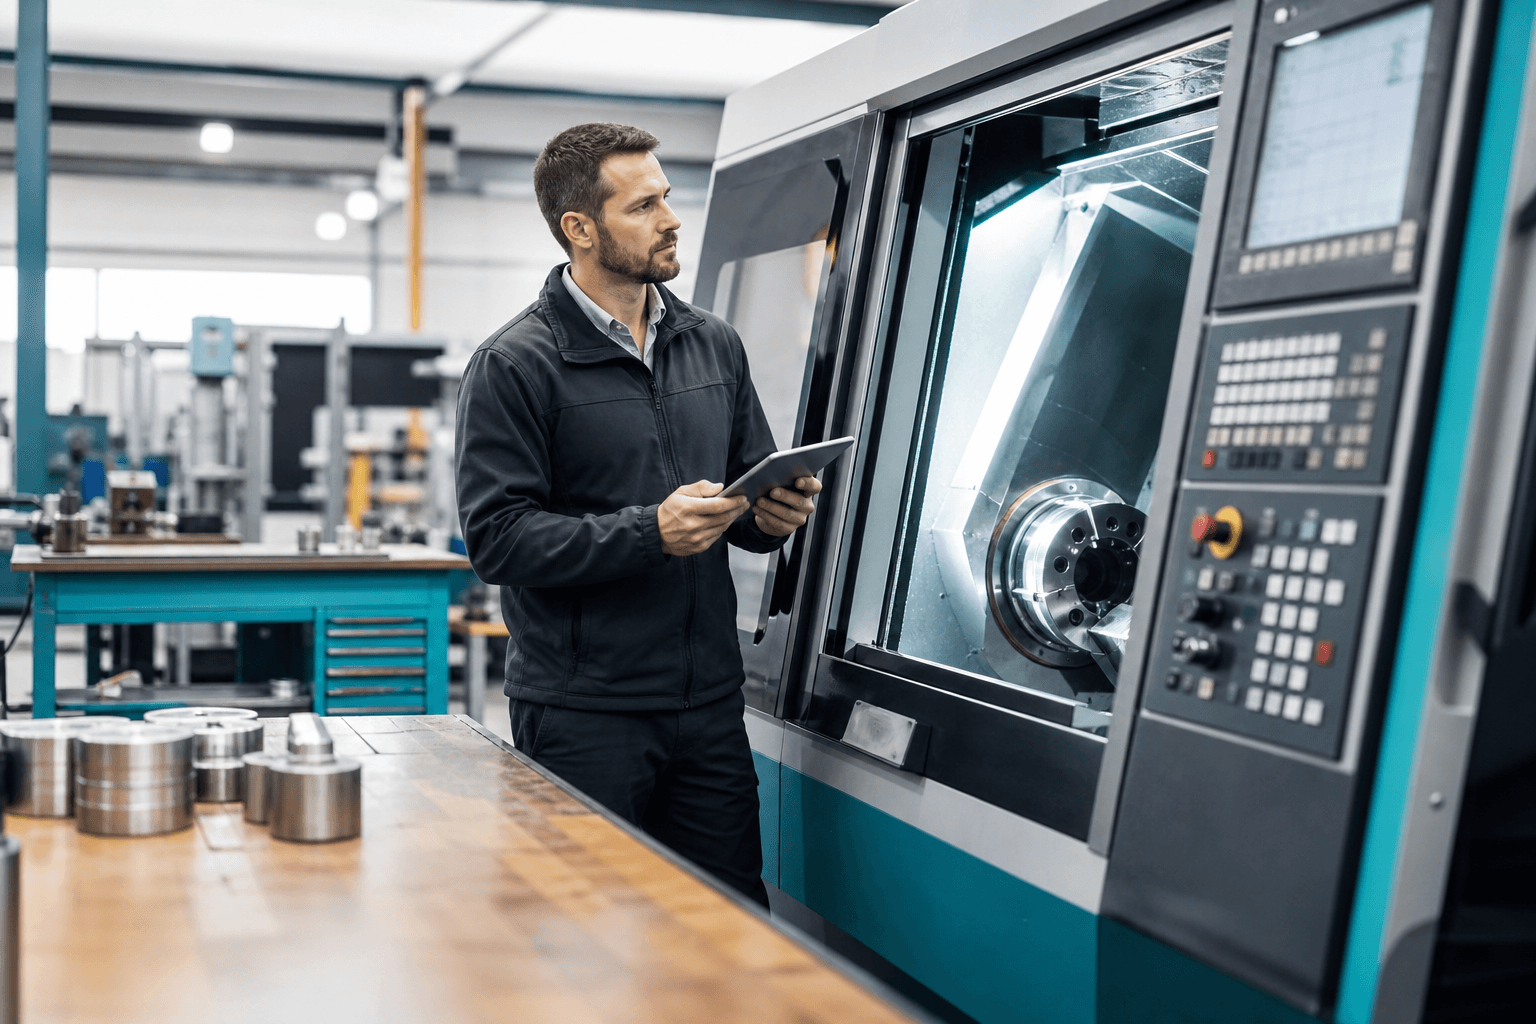
A new CNC machine can increase capacity, improve consistency or allow an engineering business to take on work that its existing equipment cannot handle. It can also require a substantial upfront investment before the machine has produced a single component. CNC machine finance allows a business to spread some or all of the cost over an agreed period rather than paying the full purchase price immediately. Depending on the equipment, supplier and applicant, possible routes may include hire purchase, finance leasing, other equipment-leasing structures, asset refinance or a business loan. The appropriate structure depends on whether the business wants to own the machine, how long it expects to use it and what it can comfortably afford. Finance is subject to status, lender criteria and approval.
What is CNC machine finance?
CNC machine finance is business funding used to acquire machinery controlled through computer numerical control.
Instead of paying the entire cost from available cash, the business enters into a finance agreement and makes payments over an agreed term. The machine will normally be central to the agreement, although the ownership position and end-of-term arrangements vary between finance products.
CNC equipment financing is a more specific subject than general business or asset finance. The lender may need to understand both the applicant's ability to make the payments and the machine being acquired.
That can involve questions such as:
- What type of CNC machine is being purchased?
- Is it new or used?
- Who is supplying it?
- What will it manufacture?
- Is installation, training or tooling included in the quotation?
- Does the machine have an identifiable value and secondary market?
- How will the investment affect the business's capacity or efficiency?
For an overview of the wider product category, see Tera's guide to understanding asset finance.
What CNC equipment could potentially be financed?
Finance may be considered for a range of CNC and precision-engineering equipment. Availability depends on the lender, the business and the individual asset.
Potential examples include:
- CNC milling machines
- CNC lathes
- machining centres
- turning centres
- three-axis, four-axis and five-axis machines
- CNC routers
- laser-cutting machinery
- specialist production machinery
- automation or ancillary equipment associated with a production process
- tooling, where it forms an acceptable part of the transaction
Not every cost shown on a supplier's quotation will necessarily be financeable under the same agreement.
A machine may have a serial number, identifiable market value and a useful working life. Bespoke tooling, software, transportation, installation and operator training may have different characteristics. A lender may therefore separate these elements or decide that some costs require another funding structure.
Businesses should provide an itemised quotation so that the machine, tooling and associated costs can be considered clearly.
Tera's existing CNC and precision engineering finance page provides broader information about finance for the sector. This guide focuses specifically on funding the machinery itself.
Why finance a CNC machine?
The reasons for considering CNC machine funding are usually operational rather than purely financial. The business needs a particular capability but does not want the purchase to absorb cash required elsewhere.
Preserve working capital
Paying cash for a machine can reduce the funds available for materials, wages, energy, maintenance and other operating costs.
Finance may allow the business to retain more of its existing cash while spreading the equipment cost. The business still needs to establish that the payments are affordable and leave enough headroom for less predictable expenses.
Add production capacity
A manufacturer may have enough work to justify another machine but insufficient spare capacity to complete it efficiently.
Additional CNC equipment could reduce bottlenecks or create capacity for a particular process. A lender may want to understand whether the demand is supported by an existing order book, recurring customers or a realistic forecast.
Replace ageing equipment
Older machinery can become less reliable or more expensive to maintain. It may also struggle to achieve the tolerances, speed or automation required for particular contracts.
Financing a replacement can spread the investment rather than requiring one large payment. The business should compare the complete cost of replacement with the likely maintenance, disruption and limitations of retaining the current machine.
Support efficiency improvements
A newer machining centre may combine operations that previously required several setups. Other investments may reduce manual handling, shorten cycle times or improve repeatability.
These benefits should not be assumed. Businesses should use their own production data, supplier specifications and realistic utilisation estimates when assessing the investment.
Prepare for larger contracts
A business may need particular machinery before it can undertake a new contract or type of work.
Where the purchase depends on an anticipated contract, the business should consider what happens if volumes are lower, the start date changes or the customer does not renew. Finance payments continue according to the agreement even if expected work does not materialise.
Main CNC machine funding options
The appropriate route depends on the machine, the transaction and the business's objectives. Most of these structures sit within asset finance; a general business loan may be relevant where associated costs do not fit a machinery agreement. The following descriptions are general and are not a substitute for reviewing the terms of a specific offer.
Hire purchase for a CNC machine
Under hire purchase, the finance provider purchases the machine and the business uses it while making payments under the agreement. A deposit or initial contribution may be required.
Once all payments and any applicable final fee have been made, ownership normally transfers to the business in accordance with the agreement.
Hire purchase may suit a manufacturer that:
- expects to use the CNC machine for a substantial period;
- wants to work towards ownership;
- prefers to spread the purchase cost; and
- is comfortable taking responsibility for the machine's operation, insurance and maintenance.
The business should examine the initial payment, total amount payable, agreement term, maintenance obligations, early-settlement provisions and ownership conditions.
Finance lease
With a finance lease, the finance provider purchases the machine and leases it to the business. The business pays rentals for the agreed term but does not normally become the legal owner automatically.
End-of-term arrangements depend on the agreement. Businesses should establish in advance what options may be available and whether additional rentals, return conditions or other charges could apply.
A finance lease may be considered where the priority is using the machine rather than acquiring legal ownership.
Operating or equipment lease
An operating lease may provide use of equipment for an agreed period without the business purchasing it.
This could be relevant where the business expects its machinery requirements to change or wants to avoid retaining an asset beyond its preferred replacement point. However, the availability and terms of an operating lease will depend on the equipment and provider.
Return conditions, usage provisions, maintenance responsibilities and end-of-term arrangements should be checked carefully.
Asset refinance
Asset refinance uses value held in an asset the business already owns to raise funds. It is different from financing the purchase of a new machine.
For example, a business that owns eligible machinery could potentially use that equipment as part of a refinancing arrangement while continuing to operate it. The amount and structure would depend on the lender's assessment of the asset and the business.
Existing finance, ownership, equipment condition and current value will all be relevant. Refinancing also places an important operating asset within a new finance commitment, so the risks and total cost should be considered carefully.
Business loan or term finance
A business loan may be appropriate where the transaction includes costs that do not fit easily within machinery finance.
These could include premises work, installation, software, training or working capital associated with bringing the new capacity into operation. A loan is not automatically preferable simply because it offers greater flexibility; its security, cost, term and repayment profile must still be compared with asset-backed options.
Hire purchase or leasing for a CNC machine?
The distinction normally begins with the business's long-term intention for the machine.
| Consideration | Hire purchase | Leasing |
|---|---|---|
| Ownership | Normally transfers after the contractual payments and any applicable final fee | The finance provider normally retains legal ownership |
| Upfront cost | An initial contribution may be required | Initial rental requirements vary |
| Payments | Made over an agreed term | Rentals made over an agreed term |
| Flexibility | Often suited to retaining the machine | May suit businesses focused on use or replacement flexibility |
| End of term | Ownership normally transfers under the agreement | Options depend on the type and terms of the lease |
| Typical consideration | Long-term use and eventual ownership | Access to equipment without automatic ownership |
| Maintenance | Usually the business's responsibility | Depends on the lease |
| Early exit | Settlement terms may apply | Termination conditions and charges may apply |
Consideration
Ownership
Hire purchase
Normally transfers after the contractual payments and any applicable final fee
Leasing
The finance provider normally retains legal ownership
Consideration
Upfront cost
Hire purchase
An initial contribution may be required
Leasing
Initial rental requirements vary
Consideration
Payments
Hire purchase
Made over an agreed term
Leasing
Rentals made over an agreed term
Consideration
Flexibility
Hire purchase
Often suited to retaining the machine
Leasing
May suit businesses focused on use or replacement flexibility
Consideration
End of term
Hire purchase
Ownership normally transfers under the agreement
Leasing
Options depend on the type and terms of the lease
Consideration
Typical consideration
Hire purchase
Long-term use and eventual ownership
Leasing
Access to equipment without automatic ownership
Consideration
Maintenance
Hire purchase
Usually the business's responsibility
Leasing
Depends on the lease
Consideration
Early exit
Hire purchase
Settlement terms may apply
Leasing
Termination conditions and charges may apply
Neither route is automatically cheaper or more suitable. The correct comparison should account for:
- the total amount payable;
- any deposit or initial rentals;
- the length of the agreement;
- end-of-term payments or conditions;
- maintenance and insurance;
- how long the machine will remain useful;
- the business's cash-flow position; and
- the tax and accounting treatment applicable to the business.
Tera's asset finance calculator can estimate monthly repayments from the machine price, deposit and term. The HP versus lease versus cash calculator can illustrate different structures using the assumptions entered. Results are illustrative rather than a finance quote or tax advice.
Financing a new or used CNC machine
Both new and used equipment may potentially be considered, but a used CNC machine can require additional checks.
Machine age
Age may affect the length and type of finance available. There is no universal maximum age that applies to every lender or every CNC machine.
The lender may consider the age at the start and end of the proposed agreement alongside the machine's expected economic life.
Condition and service history
A used machine's condition may be more important than its calendar age.
Useful records could include:
- maintenance history;
- service reports;
- spindle-hour information;
- inspection or test reports;
- details of any rebuild or refurbishment;
- evidence of current operation; and
- confirmation that essential software or controls remain supported.
Supplier
A recognised machinery dealer may be easier for a lender to assess than an informal or private sale. That does not determine the outcome, but supplier identity, trading status and documentation can form part of the lender's review.
If equipment is imported, the transaction may involve additional questions about currency, delivery, installation, warranties and when title passes.
Valuation and resale market
The lender may consider the machine's present value and whether there is a market for comparable equipment.
A highly bespoke system could be valuable to the buyer but difficult to resell. This does not mean it cannot be funded, but it may affect how the proposal is assessed or structured.
Remaining working life
The proposed agreement term should make sense in relation to how long the business expects to use the machine.
A lower purchase price does not necessarily make an older machine the better investment if maintenance, downtime or early replacement is likely.
What might a lender consider?
Every lender applies its own criteria. A CNC machine finance assessment may consider a combination of the business and the equipment rather than one factor in isolation.
Possible considerations include:
- length of trading history;
- recent accounts or management information;
- turnover, profitability and cash flow;
- existing borrowing and monthly commitments;
- business and director credit history;
- the requested amount;
- deposit or initial contribution;
- machine type, age, value and condition;
- supplier identity;
- the intended use of the machine;
- the business's experience in the sector;
- existing customer demand or order book; and
- any guarantees or additional security requested by the lender.
A lender may also ask why the chosen machine is appropriate. A concise commercial explanation is usually more useful than an optimistic growth statement.
For example, the business might explain that the machine will replace an outsourced process, relieve a documented capacity constraint or add a specific capability requested by existing customers.
Illustrative example — not a customer case study
A precision-engineering company is considering a CNC machining centre priced at £100,000.
The company could pay cash, but doing so would significantly reduce the working capital available for materials, wages and the period between completing work and receiving customer payments.
It therefore compares hire purchase with leasing.
The company expects to use the machine for many years, making eventual ownership relevant. It prepares a supplier quotation, equipment specification, recent financial information and a forecast showing the effect of the proposed payments under conservative production assumptions.
No rate, payment amount or approval outcome can be assumed from this example. The available terms would depend on the machine, supplier, applicant and lender criteria.
The purpose of the comparison is to decide whether preserving working capital justifies the total cost and obligations of finance.
How to prepare for a CNC machine finance application
Before approaching a lender or broker, prepare a clear transaction file.
Equipment information
Include:
- make and model;
- serial number, where available;
- new or used status;
- year of manufacture;
- full specification;
- purchase price;
- itemised tooling and ancillary costs;
- supplier quotation;
- delivery and installation details;
- warranty information; and
- service or inspection records for used machinery.
Business information
Depending on the lender and application, information requested may include:
- recent filed accounts;
- management accounts;
- business bank statements;
- details of existing borrowing;
- ownership and director information;
- current order book or customer information;
- cash-flow forecasts; and
- an explanation of the investment.
Commercial rationale
Be ready to explain:
- why the machine is required;
- what work it will perform;
- whether it replaces or adds capacity;
- how utilisation has been estimated;
- what happens if expected demand is delayed; and
- how the payments will be met from existing business cash flow.
Tera's business borrowing calculator can help businesses explore indicative affordability assumptions, but it does not provide a lending decision or guaranteed borrowing amount.
Questions to ask before accepting CNC equipment finance
Before entering an agreement, ask:
- 1. What is the total amount payable?
- 2. Is an initial contribution required?
- 3. Who owns the machine during and after the agreement?
- 4. Are there any final payments or fees?
- 5. What are the early-settlement or termination terms?
- 6. Who is responsible for insurance, servicing and repairs?
- 7. Are installation, tooling and software included?
- 8. What happens if delivery or commissioning is delayed?
- 9. Are there restrictions on moving or modifying the machine?
- 10. What happens if the machine fails or becomes obsolete?
- 11. Has the business tested payment affordability under less favourable trading assumptions?
- 12. Has an accountant confirmed the relevant tax and accounting treatment?
Explore CNC machine finance options
The appropriate way to finance a CNC machine depends on the equipment, supplier, business finances and intended period of use. For sector-wide options — not just the machine — see finance for CNC and precision engineering businesses.
Tera Business Finance arranges finance from a panel of lenders and is not a lender. Tera may be able to explore suitable options after reviewing the requirement, but availability and terms remain subject to status, lender criteria and approval.
To discuss a particular machine, provide its specification, supplier quotation and an outline of what the investment is intended to achieve.
Sources used
Common questions
Tera arranges finance from a panel of lenders. We are not a lender. Finance is subject to status and lender terms.